Refused three times, approved in principle 37 days after a fresh application
A mid-career professional from Bangladesh, refused by the US, UK and New Zealand. What INZ found, what we changed, and what other refused applicants can learn.
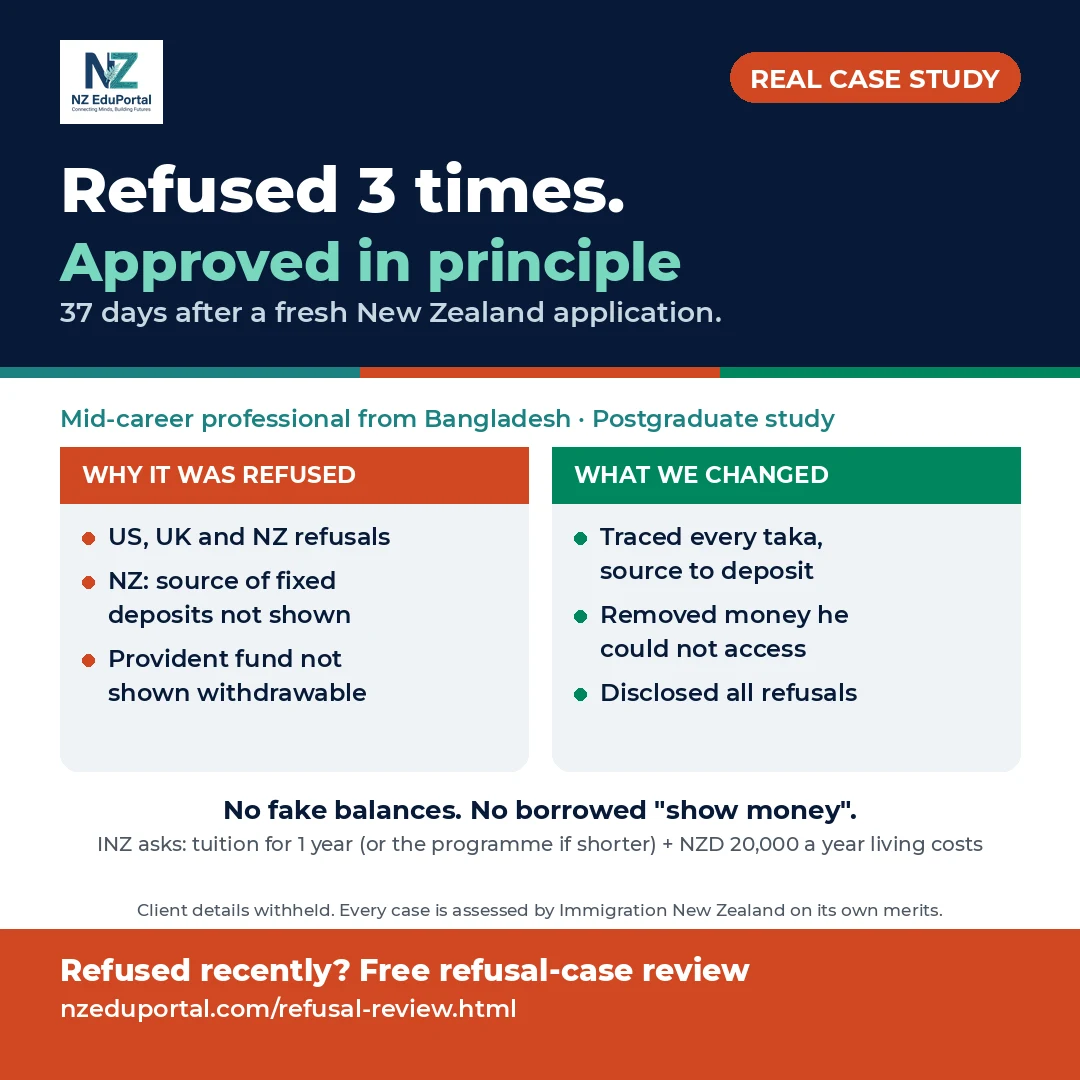
Client details are withheld. Every case is assessed by Immigration New Zealand on its own merits; this result does not predict any other outcome.
The starting point
A mid-career professional with 17 years in one job, a family in Bangladesh and a postgraduate offer in New Zealand. Before coming to us he had three refusals: a US student visa, a UK student visa (the requested documents were sent to the wrong mailbox), and a New Zealand student visa declined in August 2026.
Why New Zealand declined
INZ was not satisfied about funds for living costs under instruction U3.20, for two reasons: the source and history of three fixed deposits had not been shown, and an employee provident fund had not been shown to be available to withdraw. There was no finding of fraud.
What we changed
- Traced every taka. A transaction-by-transaction chain from the original source to each fixed deposit, with bank certificates. One gap in the paper trail was disclosed openly, not hidden.
- Removed money he could not access. The provident fund only pays out on resignation, so we took it out of the funds and used it only as evidence of his ties to his job.
- Used an acceptable loan. An education loan from a state-owned bank with sanction and disbursal letters, secured against his own property.
- Disclosed every refusal with the original letters, and corrected an old certificate that described unpaid training as a job.
- One timeline everywhere. The same dates and descriptions in the statement of purpose, history, cover letter and forms.
The result
The fresh application was approved in principle 37 days after lodgement. The student now pays tuition and sends the provider’s receipt to INZ before the visa is granted.
Lessons for other refused applicants
- Answer each reason in the decline letter with new evidence.
- Remove weak money instead of arguing for it.
- Never borrow or “show” money that is not genuinely yours to use.
- Disclose every refusal, from any country.
Refused recently? Book a free refusal review.